ETF vs. Mutual Fund vs. Index Fund: Untangling Three Terms I've Used Loosely
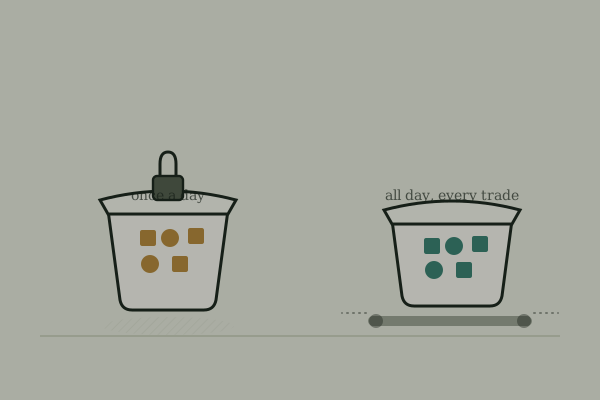
I’ve told you to buy “a broad index fund” more times than I can count on this blog, and I’ve never once clarified that “index fund” isn’t actually a type of account or a legal structure — it’s a strategy. That strategy gets sold to you wrapped in one of two very different packages: a mutual fund or an ETF. Worth actually untangling, especially before you’re staring at a brokerage app trying to decide between two tickers that seem to do the same thing.
The one-sentence version
“Index fund” describes what a fund does (track a market index like the S&P 500); “mutual fund” and “ETF” describe how it’s packaged and traded — and a huge number of index funds exist in both forms, holding nearly identical investments, with real differences in how you actually buy and sell them.
What actually separates a mutual fund from an ETF
Both can hold the exact same underlying investments — hundreds or thousands of stocks, tracking the same index. The difference is entirely in the mechanics of ownership and trading:
- Mutual funds price and trade once per day, after the market closes. Submit an order any time during the day, and it executes at that day’s single closing price (“net asset value”), determined after trading ends — you don’t know your exact execution price the moment you place the order.
- ETFs (exchange-traded funds) trade continuously throughout the day, exactly like an individual stock. You can watch the price move minute to minute, place a limit order at a specific price, or buy and sell multiple times in the same day if you wanted to.
This single difference explains most of the other practical distinctions people notice.
Why this practical difference matters
Minimum investment: many mutual funds have a minimum initial investment (often $1,000-$3,000, sometimes waived), because you’re buying directly from the fund company. ETFs trade like stocks, so you can typically buy as little as one share — and many brokerages, Robinhood included, now support buying fractional shares of ETFs, which lowers the practical entry point to whatever dollar amount you want to start with.
Cost: both can have low expense ratios for a comparable index — this isn’t really a mutual-fund-vs-ETF distinction, it’s a “which specific fund” distinction. But ETFs are more commonly commission-free to trade at most brokerages today, whereas some mutual funds (especially ones outside your brokerage’s own fund family) can carry a transaction fee.
Tax efficiency: ETFs have a structural mechanism (how new shares get created and redeemed, using an in-kind process rather than cash) that tends to generate fewer taxable capital gains distributions than a comparable mutual fund, in a regular taxable brokerage account specifically. It’s a real, well-documented difference, though a relatively minor one for a typical long-term, buy-and-hold investor — it matters more the more actively a fund trades internally.
What doesn’t actually differ
This is the part worth remembering when you’re comparing two options that track the same index: an S&P 500 index mutual fund and an S&P 500 index ETF are, underneath the wrapper, holding almost the same 500 companies in almost the same proportions. The difference isn’t in what you own — it’s in how you buy it, how quickly you can trade it, and some secondary cost and tax mechanics. Picking between them isn’t picking between fundamentally different investments; it’s picking between two ways to access essentially the same one.
When the difference actually matters for you
- If you’re investing a fixed amount on a schedule and not planning to trade intraday (most long-term investors, most of the time), the mutual-fund-vs-ETF choice is mostly a wash — pick whichever is available at a low cost through your brokerage without a transaction fee.
- If you want the flexibility to buy or sell at a specific price during the trading day, or you’re starting with a small dollar amount and want fractional shares, ETFs are generally the more accessible and flexible option today.
- If your 401(k) or workplace plan only offers mutual fund options (common — employer plans often don’t offer ETFs at all), that’s simply the wrapper available to you there, and the underlying index-tracking strategy still works the same way.
The takeaway
“Index fund” tells you the strategy; “mutual fund” or “ETF” tells you the packaging. Once you know that, a ticker like VOO or VTI stops being a mystery — it’s very likely the same basic idea as an S&P 500 or total-market index mutual fund, just in the form that trades like a stock, with fractional shares and same-day pricing as the practical upside. Neither wrapper is a trap; the real decision, as always, is still mostly about the expense ratio and how broad the underlying index actually is.
Discussion